TL;DR
A teaser (also called a blind profile or no-names summary) is a one-page, anonymous summary of a business, sent to a broad buyer list before any NDA is signed. It states what the company does, how big it is, why it is attractive and what the buyer should do next. It does not name the company, its customers, its town or its owners. The teaser is a filter: its specificity decides who raises a hand, so it needs to be detailed enough to attract the right buyers and vague enough to protect the seller. Written well, it is the cheapest document in the process to produce and one of the easiest to get wrong.
A teaser that is too generic attracts everyone and dilutes competitive tension. A teaser that is too specific identifies the seller before an NDA exists. The craft is choosing which facts to keep exact (size, margins, growth, recurring revenue) and which to generalize (location, customer names, product names).
What is an M&A teaser?
A teaser is the first document a seller's adviser sends to a prospective buyer. It gives enough information to spark interest, and the common description is a page or a few paragraphs at most (BIC Magazine). It is anonymous, so the company is described in broad terms, for example a specialty services company based in a broad region rather than a named city.
The teaser sits at the front of a gated sequence: teaser, then NDA, then CIM, then indications of interest. That order controls who receives sensitive information and when (IMAP). Sending a CIM before an NDA, or to unqualified parties, reduces your control over the process.
In practice the teaser is usually sent by the adviser, often after a phone call to check whether the buyer is looking at acquisitions in the sector (BIC Magazine). The email is a short cover note and the teaser is the attachment. A good buyer decides from the teaser alone whether to ask for an NDA.
Teaser vs CIM: what each document does
The two documents share a source (the same data room and the same positioning), but they do different work.
| Teaser | CIM | |
|---|---|---|
| Purpose | Generate interest, protect identity | Give buyers enough to submit a credible indication of interest |
| Length | One to two pages | Often 30 to 80+ pages |
| Seller named? | No | Yes |
| NDA required? | No | Yes |
| Financials | Ranges or headline figures | Full historicals, KPIs, margins, working capital |
| Audience | Broad list: strategics, sponsors, other investors | Only buyers who signed the NDA |
| Written when | First, in the first days of preparation | After the teaser, over several weeks |
Length and scope figures for the teaser and CIM come from IMAP's comparison. Some advisers, especially in the smaller private-company market, run a three to five page "abstracted version of the CIM" as their teaser (Morgan & Westfield). The principle holds either way: the teaser is a derivative of the CIM, so it should be written from the same facts, not invented separately. See how to create a CIM for the document that follows.
The practical consequence: write the CIM's executive summary and investment highlights first (or at least in parallel), then compress them into the teaser. Teasers written in isolation tend to drift from the CIM, and buyers notice when the numbers shift between documents.
The one-page teaser structure, section by section
There is no regulated format, but most one-page teasers converge on the same six blocks.
1. Header and code name
A project code name (a neutral word, not related to the company, its products or its location), a sector descriptor and a confidentiality legend. Assign the code name to all documents in the process so every later file lines up with the teaser (Deal Memo).
2. Business description
Two to four sentences. What the company sells, to whom, and how it makes money. Use the category language buyers search and screen on, and describe geography at the region or country level, not the town.
Weak: "A leading provider of innovative solutions to a diverse customer base."
Strong: "A provider of recurring inspection and maintenance services to commercial property owners across a multi-state region, under multi-year service agreements."
3. Investment highlights
Four to six bullets. Each should carry one fact a buyer can screen on, not an adjective. The highlights worth including are the ones that survive anonymization: recurring revenue share, retention, customer diversification, proprietary equipment or software, patents, master service agreements, and market position (BIC Magazine).
4. Financial summary
A small table. Revenue and EBITDA for the last three to five years plus a few years of projections, using adjusted EBITDA if there are significant add-backs (BIC Magazine). Some advisers show ranges instead of exact figures to reduce the chance of identification (IMAP). Whichever you choose, the figures must reconcile to the CIM and the data room.
5. Transaction overview
What is being sold (100% of equity, a majority recapitalization, an asset sale), what the seller wants to achieve (growth capital, succession, partial liquidity) and the timeline at a headline level. Avoid stating a price. Brokers sometimes include an asking price; banks running auctions usually do not.
6. Call to action
One sentence on how to proceed: sign the NDA and the CIM follows, plus a named contact at the advisory firm. Nothing else.
The teaser should never feel like a mini-CIM. If a reader can reconstruct the company from the teaser plus a ten-minute web search, it has too much in it.
What buyers actually screen for in a teaser
A teaser gets seconds, not minutes. Buyers read it against a mandate they already hold, which means they are checking for disqualifiers first and attractions second.
| Buyer question | Where the teaser answers it |
|---|---|
| Is it in my sector and business model? | Header descriptor, business description |
| Is it the right size? | Financial summary |
| Is the revenue quality good? | Highlights (recurring share, retention, contract length) |
| Is it growing, and is it profitable? | Financial summary, trend |
| Why is it for sale, and what is on offer? | Transaction overview |
| Is it worth signing an NDA for? | Overall specificity |
Financial sponsors tend to react to size, margins and cash generation; strategic buyers react to fit, capabilities and adjacency. A single teaser serves both, so the highlights should include one or two points of each type. If you plan to run segmented outreach, produce two short variants of the highlights block rather than two documents. For how the audience is built, see how to build a sell-side buyer list.
How to anonymize a teaser properly
Anonymity fails on small details, not on the company name. The mechanics:
- Remove identifiers from the file itself. Company name, file names, document metadata, embedded links and any pasted CIM text (PrivSource).
- Generalize unique specifics. Describe a specific named facility or customer by type, such as "a major regional hospital system" (PrivSource).
- Watch for combinations. A niche product, a region and a revenue figure can together identify a company to anyone in the industry, even when none is identifying alone.
- Remove photos and logos. Product images, facility photos and customer logos are a common leak.
- Have the seller read it. The owner knows what a competitor would recognize. Treat silence as pending, not approval (PrivSource).
- Test the send. Send it to an address you control, signed out, and check the attachment, links and reply path (PrivSource).
- Send it as an attachment, not a forwardable link. A link that can be forwarded is a leak risk (PrivSource).
Then decide who gets it. Direct competitors carry the highest disclosure risk, so walk the seller through those names before outreach. One practical approach is a hold list of direct competitors that only get contacted once other bidders have shown strong interest (Deal Memo).
The NDA gate
The teaser exists to get a buyer to the NDA. A confidentiality agreement is signed before the buyer receives more information. Typical terms include evaluation-use only, a provision that limits who inside the buyer can see the material, permission to share with outside advisers, return or destruction of materials, and an enforcement period of usually one or two years (BIC Magazine). The sellers' counsel sets the terms; sellers do not have to accept a buyer's markup as written.
The rule of thumb for what gets unlocked at each stage is "no NDA, no name" (Deal Memo). Deal Memo also reports that roughly half of buyers who show initial interest go on to sign. Treat that as a rough benchmark from one source, not a norm.
Ten common teaser mistakes
- Adjectives instead of facts. "Market leader" tells a buyer nothing. A share of recurring revenue does.
- Too generic. A bland teaser attracts many low-relevance buyers and reduces competitive tension (IMAP).
- Too specific. One identifiable customer reference or a niche positioning can reveal the company before any NDA exists.
- Numbers that differ from the CIM. Teaser, CIM and model must tie.
- Unexplained add-backs. If adjusted EBITDA is headline, say it is adjusted.
- Metadata leaks. Author names, tracked changes and file names carry identity.
- Two pages of text. If it does not fit one page with the table, cut.
- No call to action. Buyers need to know the next step and who to contact.
- Skipping seller review. The owner should approve the final version before the first send.
- Sending it to everyone. The recipient list matters as much as the document. Keep a research list of everyone considered and a separate release list of seller-approved names (PrivSource).
Differences by firm type
The core document is the same. What changes is the audience, the level of detail and who writes it.
| Boutique investment bank / M&A advisor | Business broker | |
|---|---|---|
| Typical audience | Curated list of strategics and sponsors | Wider pool of individual and small-company buyers, often through listings |
| Valuation language | EBITDA | Seller's discretionary earnings is common |
| Teaser style | Formal one-pager, code name, financial table | Short "blind listing", sometimes with an asking price |
| Distribution | Direct, personal outreach, often a call first | Listing platforms and email to a buyer database |
| Qualification | Buyer is known by name and mandate | Buyer needs screening for funds and experience |
| Who writes it | Associate or VP from the CIM | Broker, often alongside the listing |
The point for brokers: because the audience is broader and less known, the teaser carries more of the qualification burden. Pre-screening buyers' financial capacity and operational fit before the teaser or NDA stage is standard advice in that segment (Deal Memo). For boutiques, the teaser is usually paired with a personal call and a tightly managed list.
Writing the teaser from the data room
The fastest way to a clean teaser is to work from what the client has already given you, rather than starting from a blank page:
- Pull the CIM executive summary, or if the CIM is not drafted yet, the management presentation and last three to five years of financials.
- Pick four to six facts that survive anonymization.
- Compress the description to three sentences, then strip the identifiers.
- Build the financial table from the same model that feeds the CIM.
- Have the seller sign off before the first send.
Steps one and four are where most of the time goes and where the errors come from: facts are re-typed and drift. Deliverables AI drafts teasers from uploaded data-room files (CIM, financials, management presentation), cites the source behind each statement so you can check it, and can learn a firm's house style from one of its own decks. You still own the anonymization decisions and the seller's approval.
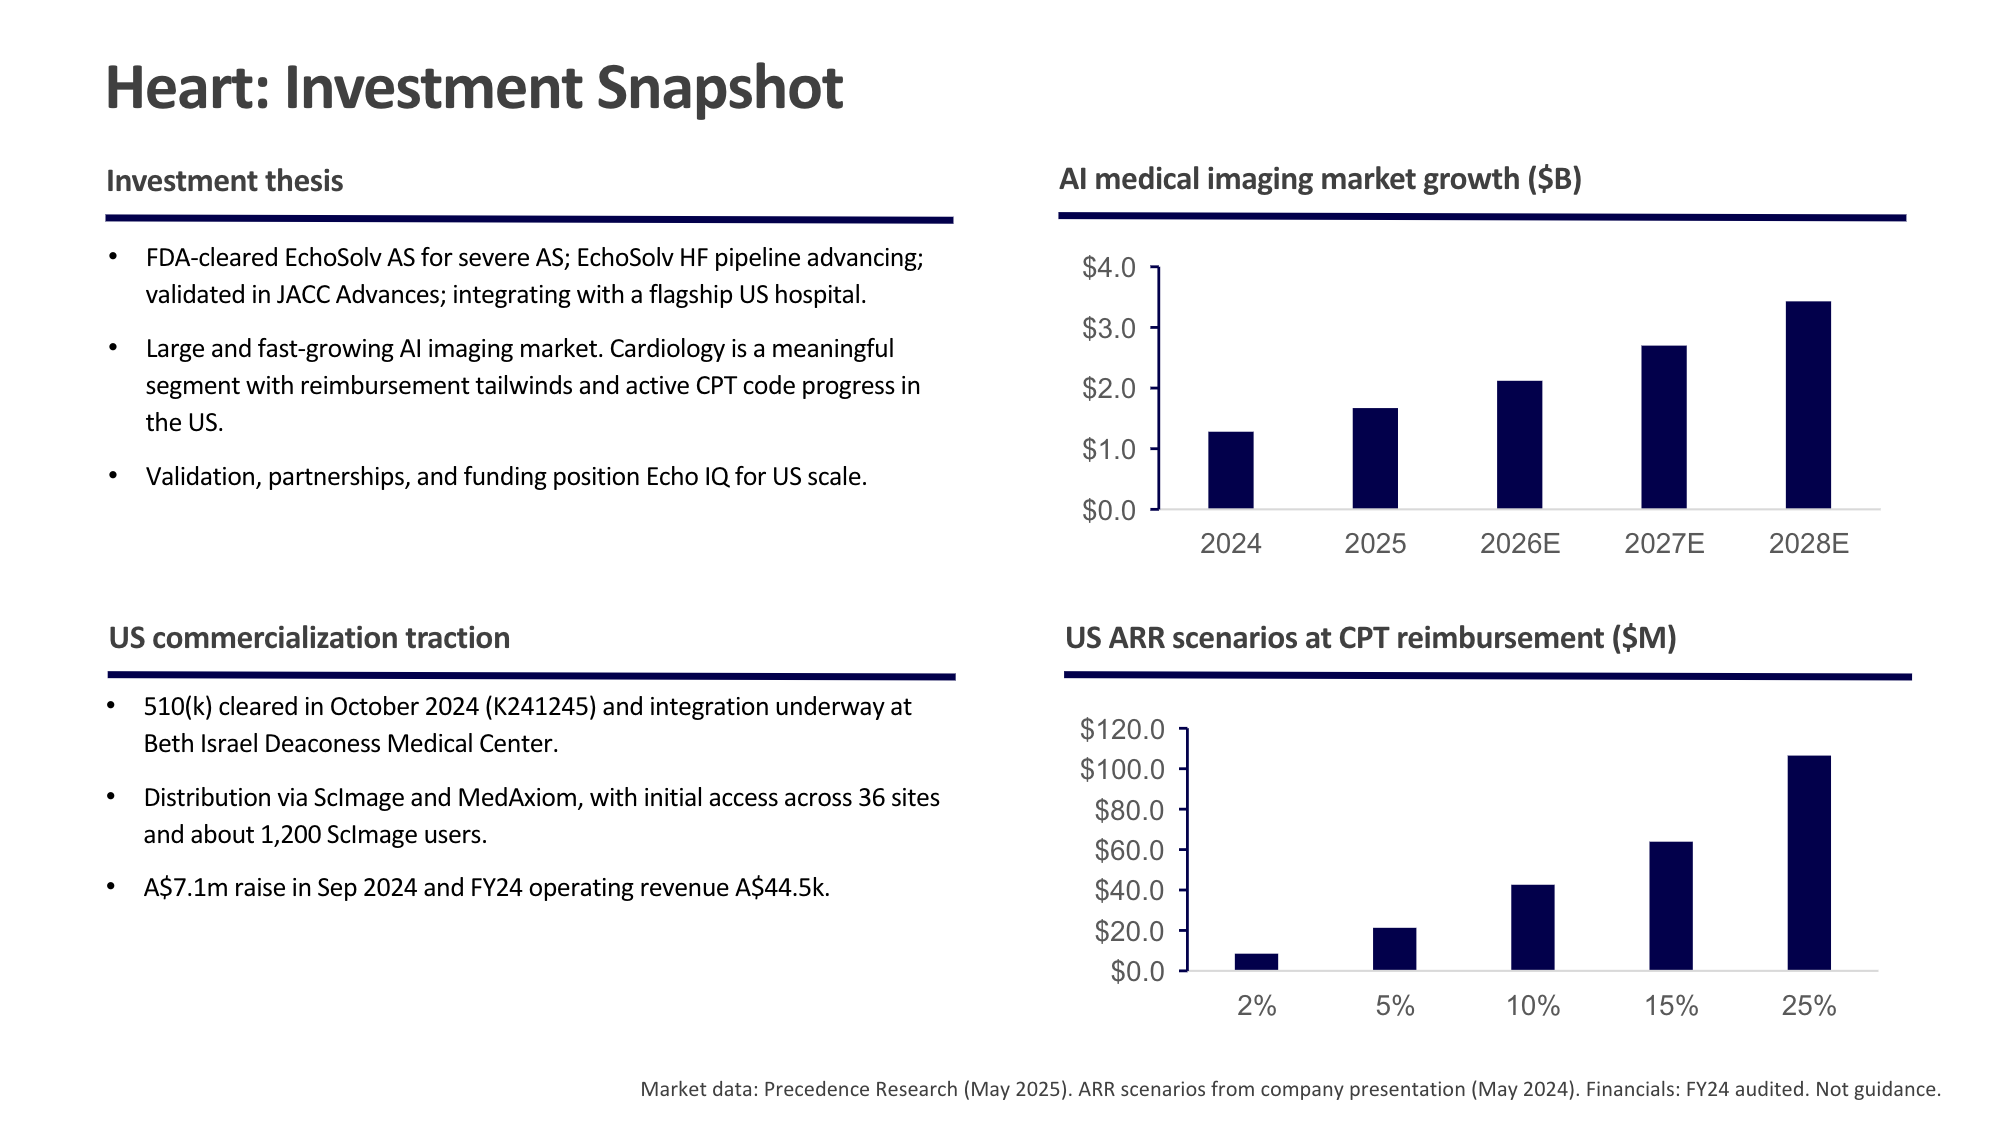
See the output. Browse a full sample CIM, slide by slide to see the source material a teaser is compressed from, or see how deal teams use Deliverables AI for CIM creation.
Using the uploaded CIM and financials, draft a one-page blind teaser for a sell-side process. Use the code name "Project Harbor". Include a three-sentence business description with region-level geography only, five investment highlights that each carry one verifiable fact, a three-year financial table of revenue and adjusted EBITDA, and a short transaction overview. Remove all customer names, locations and product names. Cite the source file behind each figure and list any detail that could identify the company so I can review it.
Frequently asked questions
What is a blind teaser?
A blind teaser (or blind profile) is an anonymous summary of a business that does not name the company. It is sent before any NDA to gauge interest. "Blind" refers to the withheld identity, not to missing financials.
How long should an M&A teaser be?
One page is the common standard, and one to two pages is the usual range. Some smaller-market advisers use three to five pages as an abstracted CIM. If it runs past a page and a half, it is likely carrying detail that belongs in the CIM.
What is the difference between a teaser and a CIM?
The teaser is anonymous, short and shared without an NDA; the CIM names the company, runs to dozens of pages and goes only to buyers who signed an NDA. The teaser sparks interest; the CIM supports an indication of interest. See how to create a CIM.
Should a teaser include the asking price?
Practice differs. Banks running a competitive process typically leave price out and let buyers bring valuation views in their indications of interest. Brokers working in the smaller private-company market sometimes include an asking price. Decide with the seller and be consistent across the process.
Should a teaser show exact financials or ranges?
Both are used. Ranges reduce identification risk; exact figures give sponsors a better screen. Whatever you choose must reconcile to the CIM and model. If a figure is shown as adjusted EBITDA, label it.
Who should receive the teaser first?
The buyers most likely to engage, in the order that the seller approves. Competitors deserve a separate conversation with the seller before outreach. See how to build a buyer list.
Can AI write a teaser?
AI can draft one from uploaded data-room files quickly and cite where each figure came from, which removes re-typing errors. Anonymization choices, which buyers receive it and the seller's sign-off remain human decisions.
Do I need a different teaser for strategics and sponsors?
Usually not. One document with highlights that speak to both is enough. If you segment outreach, vary the highlights block and the cover note rather than producing two full documents.
Resources and references
- BIC Magazine: Assuring confidentiality in M&A deals - teaser length and contents, confidentiality agreement terms, who sends the teaser
- IMAP: CIM vs teaser, what goes in each and why it matters - length, anonymity, NDA gate and filtering effect
- PrivSource: How to share a deal confidentially - identifier removal, recipient lists, send checklist
- Morgan & Westfield: Preparing an information memorandum - teaser as abstracted CIM, buyer screening in the private-company market
- Deal Memo: Maintaining confidentiality in buyer outreach - code names, "no NDA, no name", hold list, NDA conversion benchmark
Get started with AI-powered teaser creation
Ready to produce a clean, consistent teaser from the same data room as your CIM? Deliverables AI drafts teasers, CIMs and buyer lists from your uploaded files, with cited sources, in your firm's house style. Start with a full sample CIM or read the CIM creation use case.